AI euphoria gives way to fear and 'face-ripping volatility'
Published in Business News
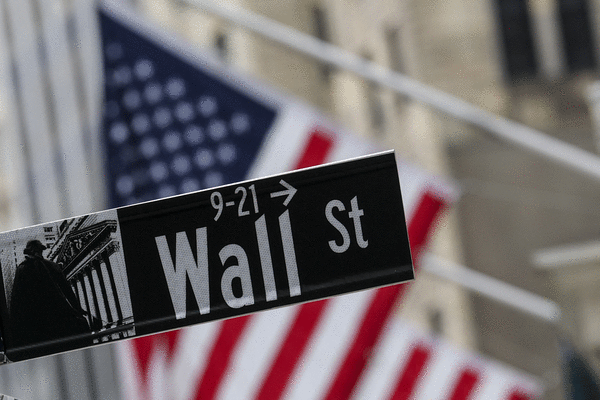
All year, investors have gorged themselves on whatever the AI trade served up. Hundreds of billions of dollars of stock sold to build out infrastructure. Near-daily bond offerings to pay for chips and data centers. History’s two largest IPOs.
This week, the rush to buy gave way to a rush for cover.
Tech stocks got pounded from New York to Seoul. Anthropic PBC shares almost erased their IPO pop. Money flowed into Treasuries, fast. The S&P 500 entered a correction in its longest losing streak since the 2020 crisis. The Nasdaq 100 sank to the brink of a bear market.
Scott Bauer had just walked off the Cboe trading floor in Chicago. One broker there had a phrase for the swings, Bauer recalled: “face-ripping volatility.” But there was no disruption to trading. It was “very busy, very orderly,” said Bauer, chief executive officer of Prosper Trading Academy.
Bauer was watching for the next Nvidia headline. He was also finding trades in the turmoil.
There’s no shortage of reasons for the turbulence. Stubborn inflation keeps the risk of another Federal Reserve rate increase alive, while strains in credit threaten to make the next round of data centers more expensive to finance.
Amplifying the impact is the massive amount of new equity and debt that investors are being asked to pony up for — supply that is testing the capacity of markets to absorb it. For much of the past two decades, U.S. companies took more shares off the market than they put back. Next year, they look set to become net sellers. Corporate bond sales could set a record.
To Adam Rich, the selloff after one record IPO was a warning for the companies lining up to raise money next year.
“Once Anthropic started trading, the market just absolutely puked, and that’s because they raised $100 billion — it’s a big, big number,” said Rich, deputy chief investment officer at Vaughan Nelson. “So my concern in 2027 for these companies is, is there enough liquidity to actually support them to do it?”
How much money is available is only part of it. Investors still have to decide who gets it, and at what price. Even booming corporate earnings can’t tell them which companies will still have an edge after the next tech breakthrough.
Competition for capital has rarely been this fierce across assets. And with more deals on offer, investors can demand cheaper shares or higher yields — or pass. Anthropic led $125 billion in U.S. share sales this week, the most in more than a decade, data compiled by Bloomberg show. Secondary offerings are also on the rise as firms including Alphabet Inc. and Meta Platforms Inc. rushed to tap the equity market for fund raising in recent months. This week, SpaceX sold $32 billion of debt at yields topping 8%, hardly levels typically associated with investment-grade debt as investors demand a premium for AI risk.
Bryce Doty, a bond fund manager at Sit Investment Associates, is watching what investors might sell to make room for the new deals.
‘’The question is, OK, if this company is able to raise money, who is the loser?” he said. ‘’What bonds were sold to be able to pay for that? How levered is the market getting?”
The volume he’s tracking isn’t just from tech companies: Utilities, too, need money for construction. For his own portfolio, Doty is looking for both shelter and bargains. “We’re trying to find a little protection from the wind, while also simultaneously looking to pick up some attractive opportunities,” he said.
The pipeline is getting bigger. With AI giants such as OpenAI expected to go public, net equity issuance next year is poised to turn positive for the first time since 2000, according to estimates from Goldman Sachs Group Inc. strategists. They also expect investment-grade and high-yield bond sales to reach $2.8 trillion, the highest in at least a decade.
More deals give investors more room to pass. With the Fed expected to hike rates in coming months and geopolitical uncertainty lingering, companies may be under pressure to juice up offerings to attract buyers, according to Andrea DiCenso, a portfolio manager at Loomis Sayles.
“It’s not a default concern. It is a price concern though,” she said at a media briefing this week. “What we are watching most closely is the concessions that you’re getting in new issues.”
Sentiment was already fragile heading into Anthropic’s debut. Cyber attacks and major technology outages broke out almost every day. Fed Governor Christopher Waller suggested a half-point rate hike was on the table. A short seller’s report on Advanced Micro Devices Inc.’s ties to China revived concern that export controls could pose another political speed bump to the AI complex.
What started as an unwind of the crowded trade has morphed into a wider selloff in risky assets. And losses deepened on Friday after a report that the U.S. Securities and Exchange Commission is investigating the accounting practices of Nvidia Corp. Bitcoin fell below $60,000 to a two-year low. Junk bonds slipped for another week as yields surged to a 19-month high. Down in all but one week since early October, the Nasdaq 100 sat within 50 points away from a bear-market decline of 20%.
As traders stepped back from risky assets, they sought safety in Treasuries, pushing 10-year yields below 5%.
“With only six weeks left of the year, there is a shift to protect the portfolio as opposed to be on the offensive side,” said Daniel Kirsch, head of options at Piper Sandler & Co. “The topic of funding is getting more attention with yields widening and questions being asked ‘why take out debt at these yields with so much market cap in equities?’”
Chris Retzler, a portfolio manager at Needham Funds, is relatively sanguine. To him, the oversubscription for Anthropic’s IPO is a sign that the window for raising capital is still wide open. When the Claude chatbot maker starts to spend that money to buy chips and compute power, he says, it’ll feed positively into the AI ecosystem.
“You now have a large player in AI that has funding and can make investments, can pay the suppliers, the picks and shovels that make them successful,” he said. “That’s where I could see the market now beginning to broaden out.”
The spending race is continuing even as analysts expect revenue growth to slow. Sales growth for AI firms in the S&P 500 is projected to weaken from 35% in the third quarter to below 25% by the end of next year, analyst estimates compiled by Bloomberg Intelligence show. While that pace still is solid, easing momentum casts doubt on whether the cohort can generate cash fast enough to sustain aggressive capital spending. Cash is draining relative to investment outlays, with a ratio falling to a level that’s nearly one fifth of where it was three years ago.
“Lower cash levels have pushed the AI basket toward debt markets to help fund the build-out, while further rate hikes could increase the cost of new or refinanced debt,” BI strategists Nathaniel Welnhofer and Christopher Cain wrote in a note. “Delivering sufficient returns on these investments is becoming increasingly important as investors focus more closely on the payoff from AI spending.”
(With assistance from Micah Barkley and Emma Haidar.)
©2026 Bloomberg L.P. Visit bloomberg.com. Distributed by Tribune Content Agency, LLC.
Comments